kally
Kally specializes in crafting sophisticated non-alcoholic beverages using organic ingredients, with a focus on California chardonnay verjus. Its range includes robust wine alternatives like Early Cabernet and Early Chardonnay, which are designed to complement a variety of meals. Kally also offers sparkling options such as Golden Sparkler and Rose Sparkler, known for their vibrant bubbles and natural sweetness, making them ideal for celebrations or pairing with diverse dishes.
Shelf presence
Brand Power (0-100) blends four shelf signals. Price position is shown below for context · a value↔premium read, not part of the score.
carried in 1 of 24 Bay Area grocers. how many stores stock the brand.
7 products in the catalog. how deep the product line is (saturating).
spans 1 category. how many categories the brand plays in (saturating).
Where it owns shelf
each bar is the % of that category's SKUs that are Kally (full bar = 100% of the shelf), grouped by department.
Most similar brands
closest to Kally in what it makes — matched on product name, category & description across the whole catalog, wherever they’re sold. Not who it competes with on the shelf.


The lineup
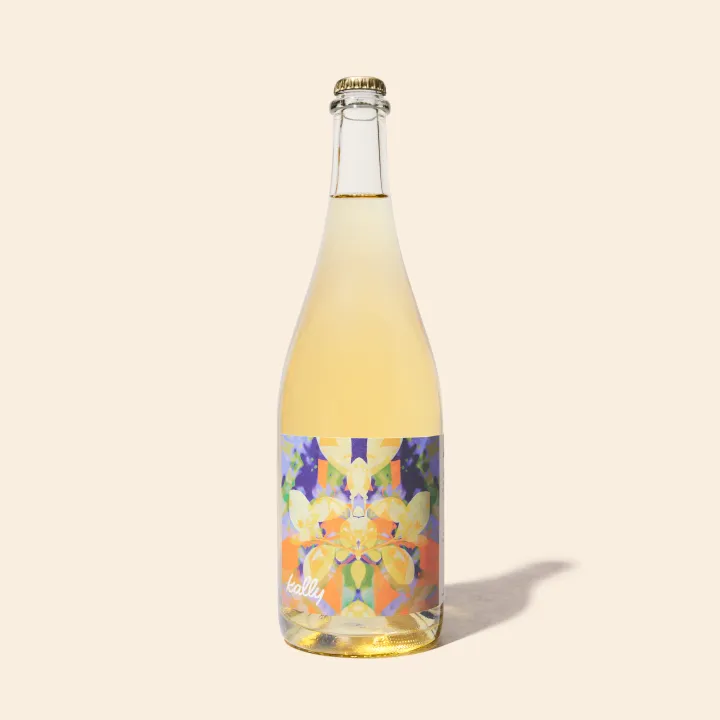
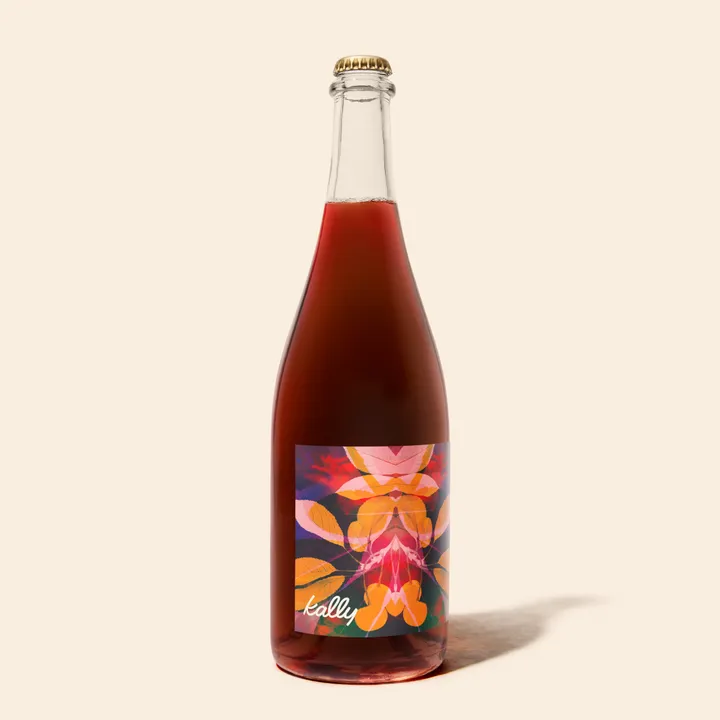
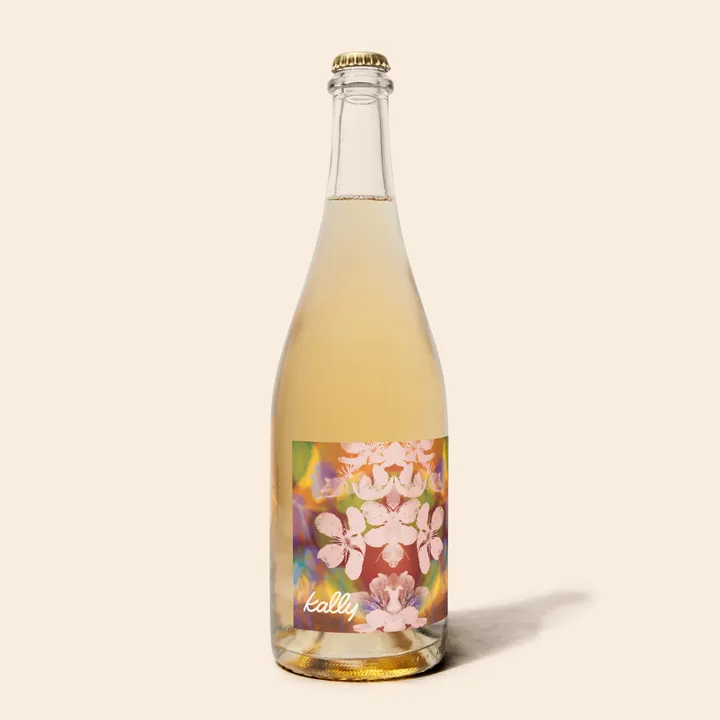
the full Kally lineup · on SF shelves first (cheapest first), then SKUs we've catalogued but haven't measured on a shelf here yet.
Sold at
Where to find Kally · Bay Area
4 storefronts across 1 grocer carry it · tap a pin to open the store.
Opportunities
Bay Area grocers where neither the digital catalog nor our shelf photos show Kally· but the shelf it belongs on is already there, ranked by fit. Fit blends category coverage, rival presence, price-band match, and openness to independents at this scale; weigh the footprint chips and route notes against it · a 7-door chain and a single great shop are different prizes. Our capture is partial, so a widely-distributed brand may already be carried through channels we don’t index.
Lead with Kally Rosé Sparkler (non-alcoholic wine alternative) · its most-distributed SKU (1 door) in Non-Alcoholic Wines, the biggest opening. The closest open door is Berkeley Bowl.

